Chinese Auto Exports to EU Hit 1.83 Million Units: The Plug-in Revolution Reshaping Global Supply Chains
Chinese Auto Exports to EU Hit 1.83 Million Units: The Plug-in Revolution Reshaping Global Supply Chains
Category: Industry Trends | Date: 2026-11-02
Executive Summary
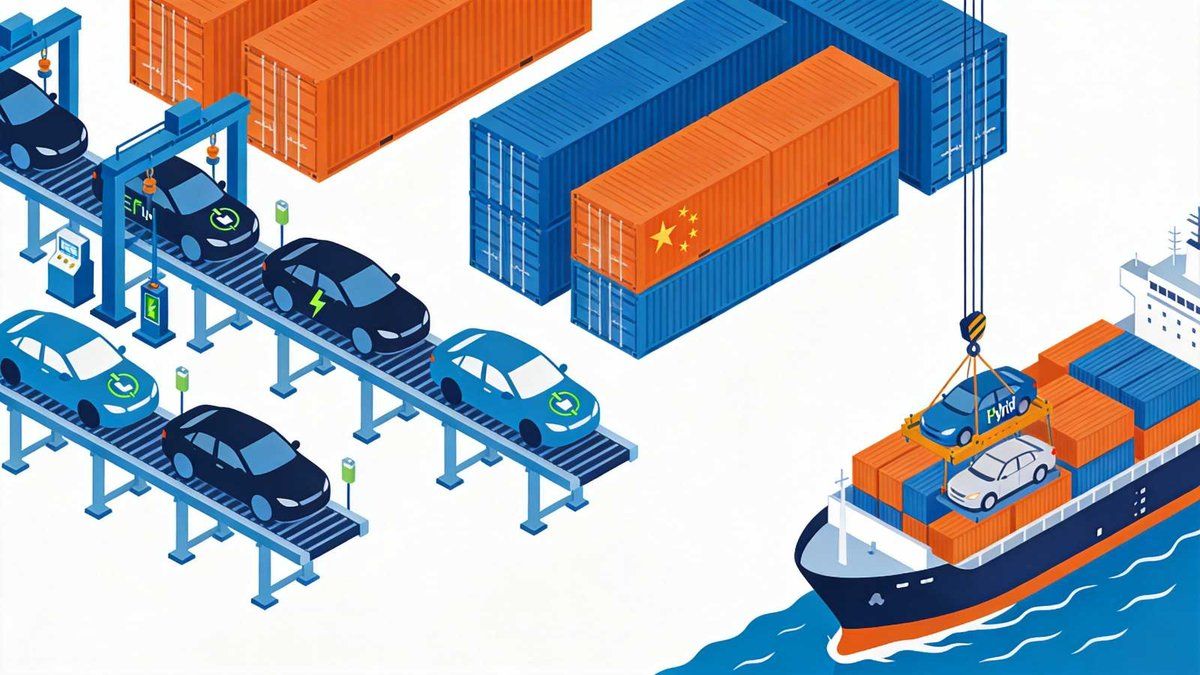
China shipped 1.83 million vehicles to the EU in Q1-Q3 2026, surpassing the full previous year -- plug-in hybrids alone jumped 372% to 654,000 units -- signaling a fundamental realignment of the global automotive supply chain that will determine which companies thrive and which get left behind as the EU's electrification mandate accelerates.
The Scene in Brussels
Picture a procurement manager at a European automotive tier-one supplier, sitting through a supplier review meeting. On the screen is a presentation from BYD -- the company's new battery-integrated chassis, the battery thermal management system, the motor control algorithms all running a simulation of compatibility with their vehicle platform. This manager has been evaluating Chinese suppliers for two years, and the conversation has shifted dramatically.
Two years ago: "Can you meet our price targets?" Today: "Can you integrate your technology into our platform?"
The difference is everything. China's auto export surge to Europe is not about cheap cars anymore. It is about Chinese manufacturers bringing integrated technology solutions that European suppliers cannot easily replicate -- and European supply chains are adapting accordingly.
The Data Behind the Surge
The numbers from China's Passenger Vehicle Association are unambiguous. January through September 2026 delivered 1.83 million vehicle exports to the EU, a volume that dwarfs the 2025 full-year total. But the headline number hides an even more revealing story beneath the surface.
Plug-in hybrid and range-extended vehicles -- often dismissed in earlier Western automotive commentary as a Chinese-market-only phenomenon -- exported 654,000 units to Europe, up 372% year-over-year. Pure electric vehicles contributed 267,000 units, also up 185%. The plug-in category is growing nearly four times faster than the pure electric category, which signals something important about European consumer preferences and procurement priorities.
European buyers are not ready to go all-electric overnight. Range anxiety, charging infrastructure gaps in rural areas, and industrial policy preferences for transitional technologies are all factoring into procurement decisions. Plug-in hybrids offer a pragmatic bridge -- significant emissions reduction with zero range compromise. Chinese manufacturers who bet early on this technology pathway are now reaping the rewards.
The Battery Supply Chain Bottleneck
The plug-in hybrid export surge carries a critical implication for battery component procurement. Every plug-in hybrid vehicle requires battery cells, battery management systems, thermal management components, and power electronics -- all of which represent significant sourcing opportunities for procurement teams working in the energy storage and automotive sectors.
China's battery supply chain advantage is not just about cost -- it is about ecosystem integration. Lithium refining, cathode and anode material production, cell manufacturing, battery pack assembly, and BMS development all operate within integrated industrial parks in the Yangtze River Delta and neighboring Guangdong province. This ecosystem provides speed-to-market advantages that are difficult for competitors to match.
For procurement teams sourcing battery components, this ecosystem translates to shorter development cycles, faster problem resolution, and more flexible production planning. Companies that have secured long-term battery supply agreements with Chinese manufacturers will benefit from supply stability during a period of growing global battery demand.
The technology spillover from automotive battery production into energy storage is accelerating. Battery management systems designed for plug-in hybrid vehicles are increasingly being adapted for stationary energy storage applications, creating procurement opportunities that extend far beyond the automotive sector. Companies sourcing energy storage solutions should recognize that the battery technology driving China's auto exports is the same technology powering the global energy storage boom.
The Technology Transfer Dimension
China's auto export surge carries an often-overlooked dimension: technology transfer. The plug-in hybrid technology that Chinese manufacturers have mastered -- battery management, thermal control, power electronics integration -- is not confined to vehicle exports. This technology is flowing into adjacent sectors through supplier relationships, joint ventures, and open-source engineering communities.
European and global component suppliers who have historically kept their technology close are watching Chinese manufacturers not just as competitors but as potential technology partners. The battery management systems in BYD's Blade Battery platform, for example, are becoming reference designs for energy storage applications across multiple industries.
For procurement teams, this technology spillover creates opportunities that extend far beyond automotive sourcing. The battery technology, motor control algorithms, and thermal management systems developed for plug-in hybrid vehicles are directly applicable to electric forklifts, commercial vehicle fleets, stationary energy storage, and even portable power solutions. Understanding these technology linkages is essential for procurement teams who want to maximize value from their automotive sourcing relationships.
The Aftermarket and Service Parts Opportunity
While vehicle exports dominate the headlines, the aftermarket and service parts segment represents another significant opportunity for procurement teams.
As Chinese vehicles penetrate European markets more deeply, the demand for replacement parts, maintenance components, and repair services grows proportionally. Unlike new vehicle sales, which are concentrated and periodic, aftermarket demand is continuous and predictable -- making it an ideal candidate for structured, long-term sourcing strategies.
Service parts procurement from Chinese auto manufacturers offers distinct advantages: standardized parts across vehicle models, competitive pricing, and increasingly reliable quality. Companies that build service parts supply chains with Chinese suppliers will reduce their after-sales costs while maintaining service quality standards.
The service parts market also reveals something important about Chinese manufacturers' commitment to the European market. Companies investing in European parts distribution networks, local warehousing, and technical training programs are demonstrating long-term commitment that goes beyond simple export transactions. This signals to procurement teams that these manufacturers are building the infrastructure to serve European customers for years to come.
The Charging Infrastructure Connection
The growth of plug-in hybrid exports to Europe is inextricably linked to the development of charging infrastructure. While plug-in hybrids can operate without charging, the environmental benefits and cost savings that make them attractive are maximized when charging infrastructure is available.
European charging infrastructure expansion, while progressing, remains uneven across regions. Urban areas in Western Europe have relatively dense charging networks, while rural areas and Eastern European markets lag significantly. This uneven infrastructure profile reinforces the plug-in hybrid advantage -- vehicles that can operate on electricity where infrastructure exists and on conventional fuel where it does not.
For procurement teams, this infrastructure reality has implications for fleet electrification strategies. Companies operating vehicles in regions with limited charging infrastructure should prioritize plug-in hybrid or range-extended options over pure electric vehicles. Chinese manufacturers who have specialized in plug-in hybrid technology are positioned to serve this large and growing segment of the European fleet market.
Why This Matters Beyond the Auto Industry
If you think this story is only relevant to automotive procurement teams, you are missing the broader signal. China's plug-in hybrid supply chain -- spanning battery cells, power electronics, thermal management systems, and integrated chassis modules -- is a masterclass in vertical integration and scale manufacturing. The same supply chain dynamics will ripple through adjacent sectors:
Energy Storage Systems. The battery and power electronics technology that drives plug-in hybrids is nearly identical to what powers grid-scale and commercial energy storage solutions. Chinese manufacturers who scaled up battery production for automotive applications now have massive cost advantages in the energy storage segment. Procurement teams in renewable energy, mining, and heavy industry should watch this closely.
Commercial Vehicles. Electric and hybrid commercial vehicles follow the same technology trajectory as passenger vehicles, with an even stronger economic incentive for fleet operators to electrify. Chinese manufacturers are already leading in electric buses, trucks, and delivery vehicles -- and the European commercial vehicle sector is not immune to this competitive pressure.
Component Suppliers. European and global auto component suppliers who do not incorporate Chinese-sourced battery systems, motor controllers, or power electronics into their products will face increasing cost disadvantages. The supply chain is already consolidating around Chinese technology platforms.
The BYD-Chery-Geili Triangle
Three Chinese automakers dominate the European export landscape, each with a distinct strategy that tells a different story about how Chinese manufacturing competes globally.
BYD leads in vertical integration, producing its own batteries (the Blade Battery platform), semiconductors, motors, and complete vehicles. This integration gives BYD a cost structure and technology development pace that rivals cannot match. For European procurement teams, BYD represents both an opportunity and a dependency risk -- partnering with BYD means access to cutting-edge technology at competitive prices, but also deepening reliance on a single supplier for critical components.
Chery focuses on volume and price competitiveness, targeting the European mass market with competitive pricing and broad model coverage. Chery's strength is in market reach and distribution networks rather than technological differentiation. This makes Chery a strong option for procurement teams prioritizing cost-efficiency and volume availability over cutting-edge features.
Geely (Jili) has positioned itself as the technology bridge between Chinese manufacturing and Western engineering expectations. Through its ownership of Volvo and collaborations with European engineering firms, Geely combines Chinese-scale production with European-quality standards. For procurement teams valuing quality assurance and regulatory compliance alongside competitive pricing, Geely offers a compelling hybrid model.
The EU Regulatory Landscape
Any analysis of Chinese auto exports to Europe must address the regulatory environment, which is shifting rapidly.
The EU's CO2 emission standards for new vehicles, effective through 2026-2030, create both headwinds and tailwinds for Chinese manufacturers. On one hand, stricter standards raise the barrier to entry for manufacturers who cannot meet them. On the other hand, plug-in hybrids -- which Chinese manufacturers have specialized in -- are positioned to benefit from transitional regulatory frameworks that recognize emissions reductions from electrified powertrains.
The EU's anti-subsidy investigation into Chinese electric vehicles remains ongoing, but its practical impact on plug-in hybrid exports has been limited so far. This is an important distinction for procurement teams to understand: the regulatory pressure is primarily targeting pure electric vehicles, not the plug-in hybrid segment where China holds its strongest growth momentum.
Supply Chain Implications for Global Procurement
The surge in Chinese auto exports to Europe has concrete implications for procurement professionals across multiple industries:
Component Standardization Pressure. As Chinese battery platforms, motor controllers, and power electronics become more prevalent in European vehicles, there is growing pressure to standardize around Chinese technology platforms. This is not a recommendation -- it is an observation of market dynamics. Procurement teams who proactively evaluate Chinese component options now will be ahead of those who react when their current suppliers are forced to switch.
Risk Diversification Strategy. Heavy concentration in any single sourcing category creates risk. The current Chinese auto export surge represents an opportunity, but also a signal that the global automotive supply chain is concentrating in specific regions and technologies. Smart procurement teams use this moment to evaluate what happens if those concentrations face disruption -- whether from policy changes, trade barriers, or geopolitical events.
What Happens Next
Three questions will define the next 12-18 months for Chinese auto exports to Europe:
Will EU tariffs on Chinese electric vehicles expand to include plug-in hybrids? If yes, the 372% growth trajectory will slow significantly. Procurement teams should prepare alternative sourcing scenarios that account for potential cost increases from expanded tariff coverage.
Will European battery and component manufacturing capacity catch up? If EU-based battery production scales faster than expected, Chinese cost advantages may narrow. This would favor procurement strategies that balance Chinese sourcing with European alternative options.
Will Chinese manufacturers accelerate European local production? Many Chinese automakers are already evaluating European manufacturing partnerships. Local production would change the competitive dynamics substantially -- reducing tariff risk, improving logistics, and potentially improving quality perception among European buyers.
The Bottom Line for Procurement Teams
China's auto export surge to Europe is not a blip. It is a structural realignment that reflects genuine technological progress, strategic product positioning, and supply chain integration that Chinese manufacturers have been building for over a decade.
For procurement teams, this means two things:
First, Chinese auto suppliers should be on every procurement shortlist for automotive components, battery systems, and related technology -- not as a last resort, but as a first consideration based on genuine competitive advantage. The technology gap has narrowed to the point where ignoring Chinese suppliers is no longer a cost-saving strategy, it is a quality and innovation risk. Procurement teams evaluating battery technology and powertrain systems across multiple suppliers benefit from structured comparison platforms. SourcingX provides the supplier intelligence tools that automotive teams need to evaluate Chinese and global suppliers across technology, quality, cost, and risk dimensions simultaneously.
Second, the plug-in hybrid segment specifically deserves dedicated sourcing attention. This is where Chinese manufacturers have established the strongest competitive position, and where the supply chain is most mature and cost-competitive. Companies that build their electrification strategy around plug-in hybrid technology sourced from Chinese manufacturers will have a significant cost and speed advantage. SourcingX provides structured supplier intelligence tools specifically designed for teams evaluating battery technology, powertrain systems, and automotive component suppliers across multiple evaluation dimensions.
For procurement teams navigating this complex landscape, having access to structured supplier intelligence -- technology assessments, quality ratings, and multi-dimensional comparisons -- is critical to making informed sourcing decisions. Teams managing automotive and component sourcing portfolios should consider structured platforms that enable holistic supplier evaluation across these critical dimensions.
FAQs
Q1: Why are plug-in hybrids growing so much faster than pure electric vehicles in European exports? European consumer demand for plug-in hybrids exceeds pure electric due to range anxiety, limited charging infrastructure in rural areas, and transitional regulatory frameworks that favor electrified vehicles. Chinese manufacturers have bet strategically on this segment, producing competitive plug-in hybrid models at prices European competitors cannot match.
Q2: Are EU tariffs likely to expand from pure electric to plug-in hybrid vehicles? Currently, EU trade measures target pure electric vehicles. Plug-in hybrids are classified differently under EU trade policy and face no tariffs. However, this could change if the EU broadens its investigation scope. Procurement teams should monitor policy developments and maintain alternative sourcing plans.
Q3: How do Chinese auto suppliers compare to European suppliers in terms of quality and reliability? Chinese auto manufacturers have significantly closed the quality gap over the past three years. Third-party quality assessments show Chinese brands achieving reliability scores within 5-10% of leading European brands in the same price segments. The gap continues to narrow, particularly in battery technology and integrated powertrain systems.
Q4: Should procurement teams diversify away from Chinese auto suppliers due to geopolitical risk? Risk management requires balanced evaluation. Chinese suppliers offer genuine technological and cost advantages in battery and powertrain technology. The optimal strategy is not to eliminate Chinese sourcing, but to diversify across multiple Chinese suppliers while maintaining some European or alternative-region options for critical components.
Q5: What is the projected growth trajectory for Chinese auto exports to Europe through 2027? Analysts project continued growth but at a moderating pace (15-25% annually, down from the current 372% plug-in hybrid surge). Regulatory developments, European manufacturing competition, and market saturation in early-adopter segments will all influence the actual trajectory.
Comments
0